If you owe more on your mortgage than your home would sell for, you still have options. A short sale lets you sell your home for less than the loan balance, with your lender agreeing to accept the sale proceeds. For many Pasco, Pinellas and Hillsborough County homeowners facing a job change, divorce, medical bills, a rate reset or a move, a short sale can be a far better path than foreclosure. Monica Karcz, a licensed Florida real estate agent with Redfin, helps homeowners understand whether a short sale fits their situation and guides them through each step.
Short Sale and Pre-Foreclosure Help
Monica Karcz assists homeowners in selling short sale and pre-foreclosure homes throughout Pasco, Pinellas and Hillsborough Counties. If you have missed payments, received a notice of default or lis pendens, or simply know your home is worth less than you owe, Monica can help you understand your options, price the home realistically, market it with the full reach of Redfin, and work with your lender through the approval process, often before a foreclosure sale date.
- Confidential, no-cost review of your situation
- Honest pricing based on a comparative market analysis
- Coordination with your lender, loss mitigation team and closing agent
- Help for sellers who are behind on payments or facing an auction date
What Is a Short Sale?
A short sale is a home sale where the price is “short” of what is owed on the mortgage and any other liens. Because the lender will receive less than the full payoff, the lender must approve the sale before it can close. You remain in your home while it is marketed, and the buyer’s offer is submitted to your lender for review.
Short Sale vs. Foreclosure
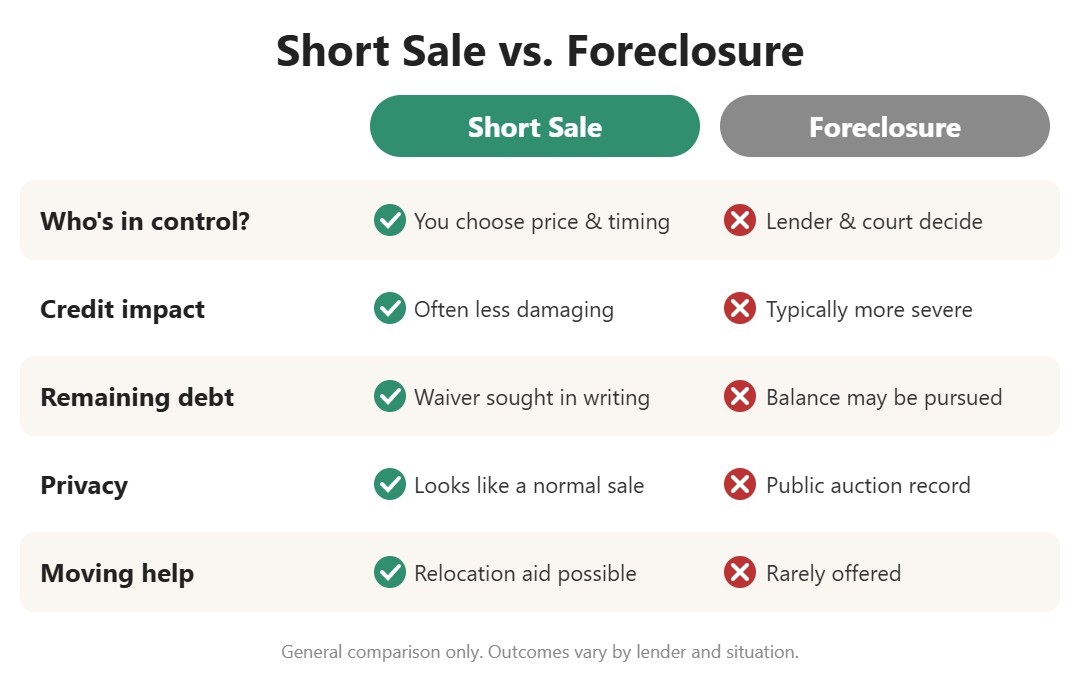
- More control: you choose the agent, the list price strategy and, within reason, the timing of your move.
- Credit impact: a short sale is still a negative credit event, but many homeowners find it less damaging than a completed foreclosure, and waiting periods for a future mortgage are often shorter.
- Privacy and dignity: the sale looks like any other listing to neighbors and buyers.
- Possible deficiency waiver: lenders can agree in writing to waive the remaining balance. Whether yours does is something to review carefully before you sign.
- Relocation help: some lender and investor programs offer relocation assistance to sellers who complete a short sale.
Do You Qualify?
Every lender sets its own guidelines, but most short sales involve three things:
- The home’s market value is less than the total owed on the mortgage and other liens.
- You have a documented hardship, such as loss or reduction of income, divorce, illness, a job relocation or the death of a borrower.
- You can provide financial documentation, typically pay stubs, bank statements, tax returns and a hardship letter.
You do not have to be behind on payments to ask about a short sale. If you are behind, the sooner you start, the more options you usually have.
The Short Sale Process: 10 Steps
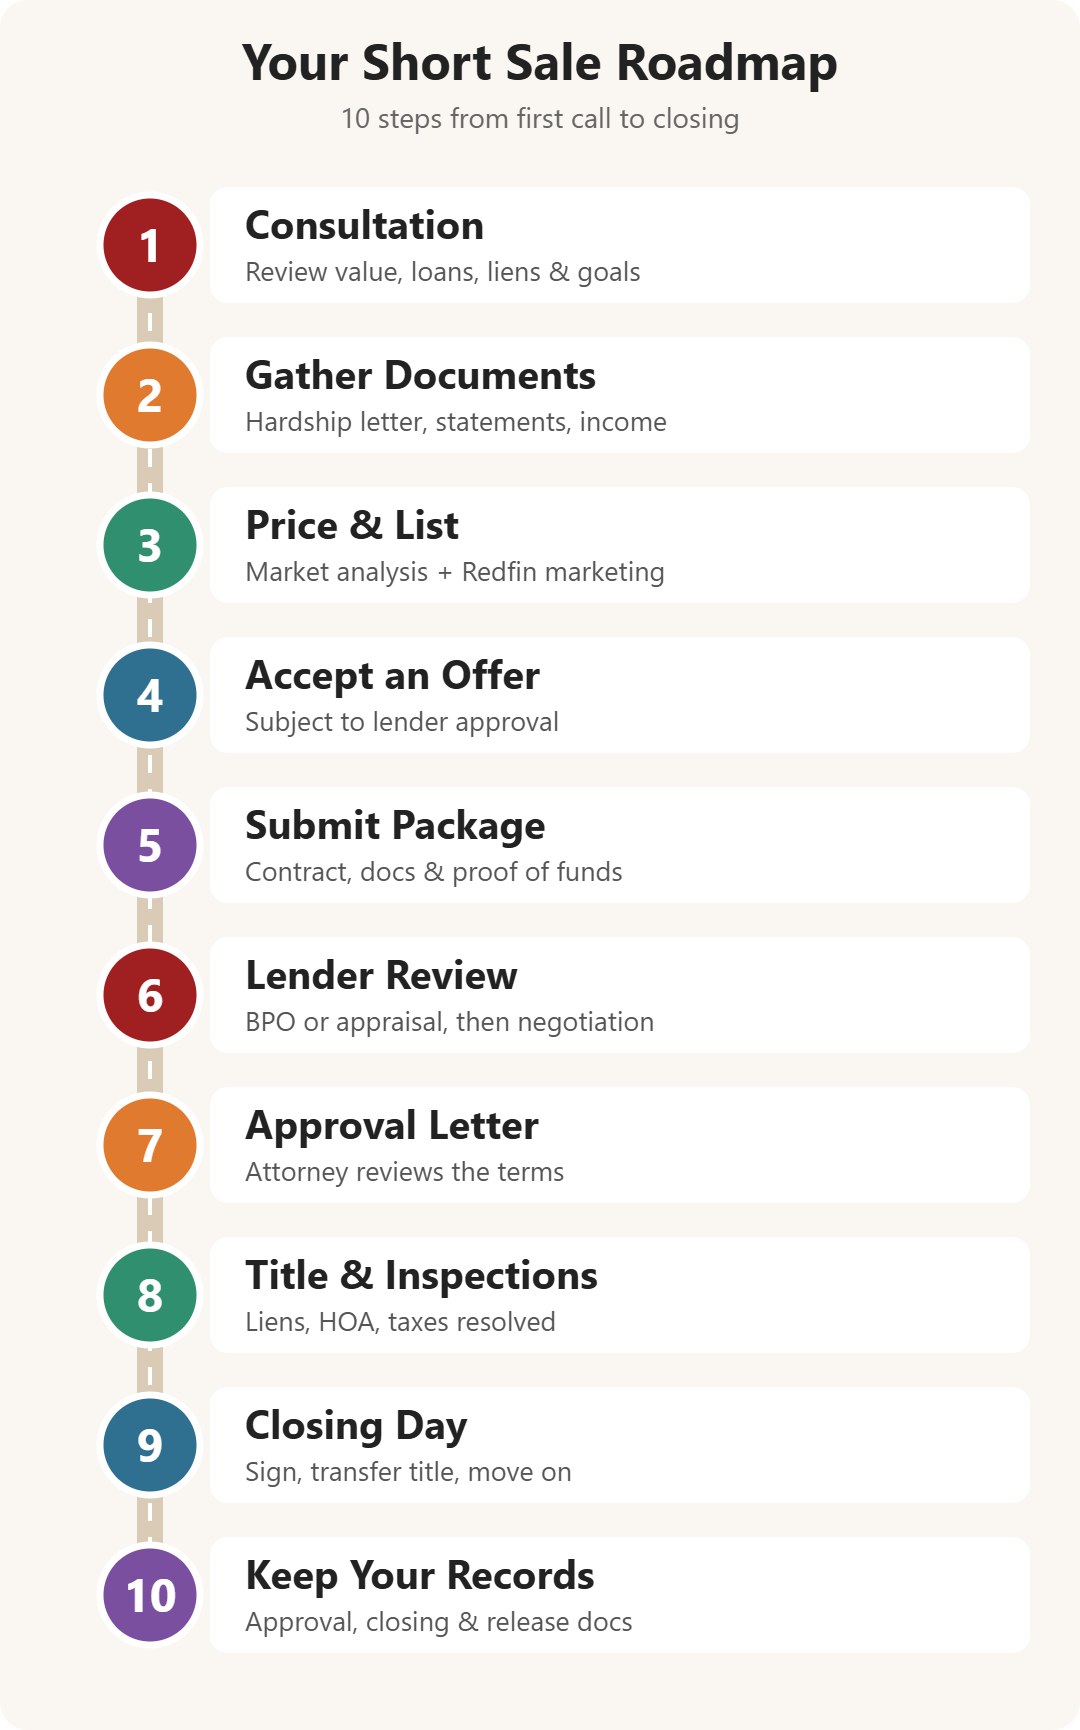
- Initial consultation and file review. We review your home’s estimated market value, mortgage information, liens, any foreclosure status, your timing and your goals. If a foreclosure case or sale date is already pending, the attorney is told right away.
- Gather the short sale package. You provide the documents your lender requires. These vary by lender but commonly include an authorization to communicate, mortgage statements, financial and hardship information, tax returns or income documents, and bank statements.
- Price and list the property. Monica prepares a market analysis, recommends a pricing and marketing strategy, lists the home, coordinates showings and finds a qualified buyer. The listing and contract make clear the sale is subject to lender approval.
- Accept an offer subject to lender approval. You sign a purchase contract with the buyer, and it becomes part of the short sale submission. Accepting an offer does not mean the lender has approved the short sale.
- Submit the complete package. The short sale package, signed contract, estimated closing statement, buyer qualification or proof of funds and other requested documents go to the lender. Other lienholders may need to approve separately.
- Lender valuation and negotiation. The lender may order a broker price opinion (BPO), appraisal or other valuation, then approve, counter, ask for more documents or decline.
- Review the approval letter carefully. If approved, the lender issues written terms that can cover the approved price or net proceeds, closing deadline, allowed costs, liens, any seller contribution, relocation assistance and deficiency language. The attorney reviews the approval and advises you on its legal effect.
- Complete inspections, title and closing requirements. Title issues, association balances, judgments, liens, taxes, buyer financing, inspections and lender conditions are resolved within the approved timeline.
- Closing. Approved proceeds are paid out according to the lender’s written approval and closing statement, and you sign the closing documents and transfer title to the buyer.
- Keep the final records. Keep the lender approval letter, closing statement, release or satisfaction documents and attorney correspondence. Ask the attorney and a qualified tax professional about any questions after closing.
Buying a Short Sale
Short sales can offer value for buyers who have flexible timing. Expect a longer approval period, homes sold as-is, and the possibility that the lender counters or declines. Monica can help you evaluate short sale listings in Tampa Bay, write a strong offer and keep the process moving.
Short Sale FAQ
Does a short sale cost the seller money?
In most short sales, the lender pays the closing costs and real estate commissions out of the sale proceeds as part of the approval. Terms vary by lender.
Can I stay in my home during the short sale?
Yes. You normally live in the home until closing.
Will I owe taxes on the forgiven debt?
Forgiven mortgage debt can be treated as taxable income in some situations, and exceptions may apply. Speak with a tax professional about your specific case.
Can a short sale stop a foreclosure?
Starting a short sale does not automatically stop a foreclosure, but many lenders will coordinate while a complete short sale package is under review. Contact your lender and a Florida attorney as early as possible.
Important Seller Expectations
- Timing varies. Short sale approval is not automatic, and lender review can take several rounds of documents and negotiation.
- Respond quickly. Lenders may ask for updated financial documents along the way. Fast responses keep your file moving.
- Do not ignore foreclosure deadlines. A pending short sale does not necessarily stop a foreclosure case or sale date. Contact Lyons Law Group right away about legal deadlines.
- Do not assume the remaining debt is forgiven. The written approval should be reviewed for deficiency language, and a waiver of deficiency is a key goal in every short sale.
- Get advice specific to you. The attorney, your lender or servicer, a tax professional and other advisers should answer questions about your own situation.
Short Sale Questionnaire
Tell Monica a little about your home and situation. It takes about 5 minutes, and you can attach photos of your home. Everything you share stays confidential. Please do not enter full loan or Social Security numbers.
Talk With Monica About Your Options
Every situation is different, and a conversation costs nothing. Call or text Monica Karcz at 813-728-1400 or schedule a confidential consultation. Serving Pasco, Pinellas and Hillsborough Counties, including New Port Richey, Holiday, Trinity, Palm Harbor, Clearwater, Land O’ Lakes, Wesley Chapel and Tampa.
This page is general information for seller education and is not legal, tax, credit or financial advice. Monica Karcz and Redfin do not provide legal advice. Short sale requirements and outcomes vary by lender, lienholder, contract and seller circumstances. Questions about foreclosure, deficiency liability, lender approval or the effect of an approval letter should go to Lyons Law Group or your chosen attorney, and tax questions to a qualified tax professional.
Our Short Sale Attorney & Title Partner
Owner & Attorney, The Lyons Law Group, P.A.
Monica’s short sale and pre-foreclosure transactions are handled together with The Lyons Law Group, P.A., a real estate law firm and attorney-owned title company in New Port Richey led by attorney Andrew “Andy” Lyons. Mr. Lyons has practiced law for more than 25 years, focusing on real estate litigation, residential foreclosure defense and mortgage modification, and the firm has served Pasco and Hernando County homeowners since 2008.
With a Realtor, an attorney and a title company working as one team, your pricing and marketing, lender negotiation, title work and closing are all coordinated from start to finish.
How Lyons Law Group Handles Your Short Sale
- Free consultation. Andy Lyons reviews your mortgage and foreclosure situation and helps you decide whether a short sale is the right fit, or whether another option such as a loan modification, case dismissal or cash for keys makes more sense.
- Financial review and hardship disclosure. The firm reviews your finances carefully before the financial disclosure goes to your lender, so nothing is missed that could delay or derail approval.
- A buyer is brought to the bank. Monica prices and markets your home with Redfin and delivers a qualified buyer whose offer is submitted with your short sale package.
- Negotiating a waiver of deficiency. The top priority in every negotiation is a written waiver in which the lender agrees not to pursue you for any remaining balance or legal fees after the sale.
- Title and closing. As an attorney-owned title company, Lyons Law Group handles the title search, lien payoffs, title insurance, escrow and closing under one roof.
The Lyons Law Group, P.A. · 4103 Little Road, New Port Richey, FL 34655 · 727-375-8900
Monica Karcz, Redfin and The Lyons Law Group, P.A. are independent businesses. You are always free to choose your own attorney and title company.